S&P Dow Jones Indices Flags Indonesia for Potential Market Reclassification
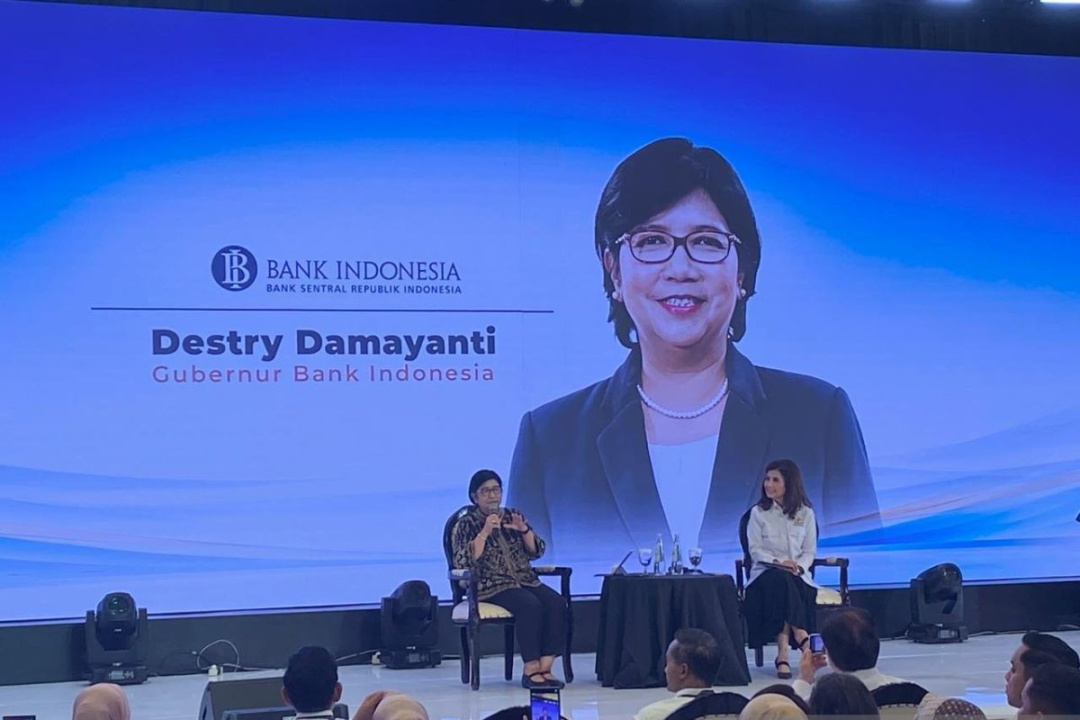
S&P Dow Jones Indices has placed Indonesia on a watch list for potential market reclassification, raising concerns about ownership transparency and free-float data in the country's equity market. This scrutiny comes as Indonesia faces pressure from other index providers, MSCI and FTSE Russell, who are also evaluating the market's compliance with emerging market standards.
The core issue revolves around the lack of clarity regarding stock ownership in Indonesia, which has led to criticisms about insufficient shareholder transparency and inadequate free-float visibility. Free float refers to the portion of a company's shares available for public trading; when this figure is unclear or artificially low, it can distort the stock's weight in an index, leading to misallocation of capital by passive funds.
For Your Trading Desk
Sponsor Spike Success.
On June 1, 2026, S&P Dow Jones Indices issued a consultation document that highlighted Indonesia's situation as part of a broader review targeting the 2025/2026 period. The company confirmed it would proceed with its standard quarterly rebalance for Indonesia in March 2026. Meanwhile, MSCI has extended its review of Indonesia's market classification to November 2026, explicitly warning of a potential downgrade from emerging market to frontier market status, which could result in billions in investment outflows.
FTSE Russell has also paused its reviews amid similar concerns, indicating that all three major index providers are questioning whether Indonesia meets the necessary standards for emerging markets. S&P Dow Jones has taken a more cautious approach compared to MSCI, opting for continued observation rather than immediate reclassification.
In response to these challenges, Indonesian regulators have announced reforms aimed at improving market transparency. These include a High Shareholding Concentration framework that proposes enhanced disclosure requirements for ownership stakes above 1% and an increase in the minimum free float to 15%. However, the effectiveness of these reforms and their timely implementation are critical as the deadlines set by MSCI and S&P DJI loom.
For investors with exposure to Indonesian equities, the immediate concern is not a sudden reclassification, as S&P DJI remains in observation mode. However, a downgrade by any major index provider could trigger forced selling from passive funds. If Indonesia can successfully implement its proposed reforms, particularly regarding ownership disclosure and free-float thresholds, it may mitigate the risk of a downgrade. The competitive dynamics among index providers further complicate the situation, as differing decisions could lead to confusion about how to appropriately weight Indonesian exposure in various portfolio benchmarks.