Cerebras Systems Faces Stock Decline but Analysts Predict Significant Upside
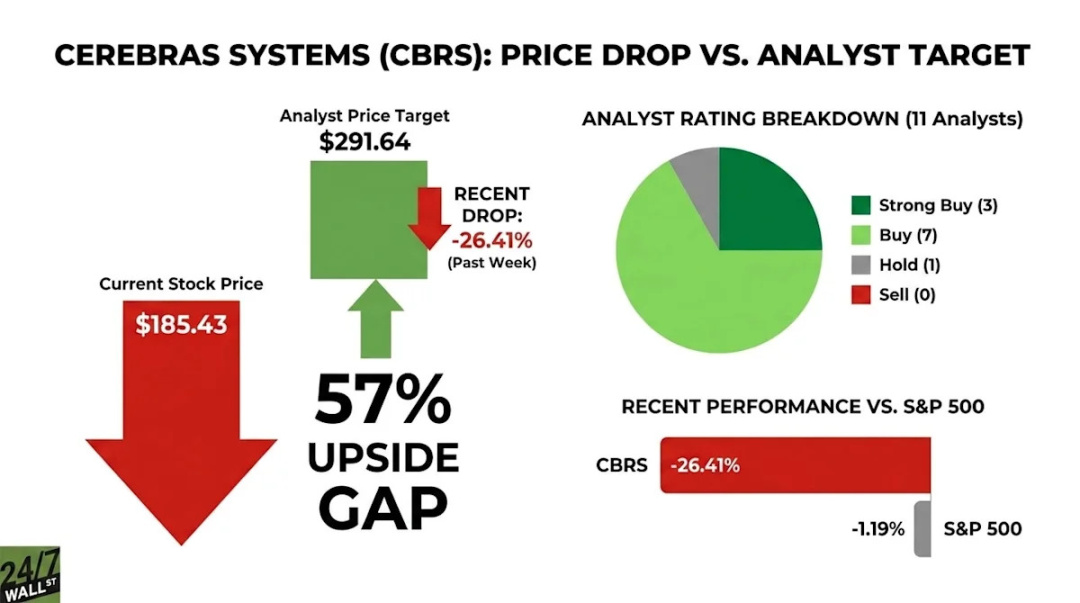
Cerebras Systems (NASDAQ: CBRS) has experienced a tumultuous year, with its stock plummeting 40% from its peak in May following a disappointing earnings report for the second quarter. Despite this sharp decline, analysts remain optimistic, with 10 out of 11 maintaining a 'Buy' rating and a consensus price target that implies a 57% upside from current levels.
The company currently trades at approximately $185.43, while the average Wall Street price target stands at $291.64. This gap highlights the analysts' belief that the recent selloff was largely company-specific rather than indicative of broader market trends, as competitors like NVIDIA and AMD saw much smaller declines of 7% and 10%, respectively, during the same period.
For Your Trading Desk
Sponsor Spike Success.
Cerebras' business model is anchored by a substantial backlog, including a significant $20 billion deal with OpenAI, which is expected to drive revenue growth. The company aims to triple its revenue by 2027, bolstered by a backlog of $25 billion in performance obligations. Analysts point to the upcoming launch of the CS-4 wafer-scale platform as a key factor that could enhance the company's market position, providing higher memory bandwidth than traditional GPU clusters.
The recent earnings report revealed a revenue of $180.11 million, which fell short of the analyst estimate of $193.55 million. Additionally, the company reported a GAAP EPS of -2.98, significantly below the expected loss of -0.1801. The guidance for Q3 indicated a core operating margin decline to between negative 25% and negative 23%, down from negative 16% in Q2, which contributed to the stock's volatility.
Despite these challenges, analysts have not significantly altered their outlooks. UBS analyst Timothy Arcuri holds the highest target at $330, suggesting an upside of approximately 78%. His analysis is based on the anticipated demand for Cerebras' innovative products and the potential for gross margins to improve as production scales.
The stock's recent performance underscores the risks involved, with shares down 26.41% in just one week. However, the broader semiconductor market has remained resilient, indicating that Cerebras' struggles are not reflective of the sector as a whole. The company’s future hinges on successful product launches and the execution of its ambitious growth plans, particularly in light of its significant contracts with major players in the AI space.
As analysts continue to express confidence in Cerebras, the market will be watching closely to see if the company can navigate its current challenges and capitalize on its growth opportunities in the rapidly evolving AI infrastructure landscape.