SK Hynix: A $1 Trillion Stock with Projected 107% Earnings Growth
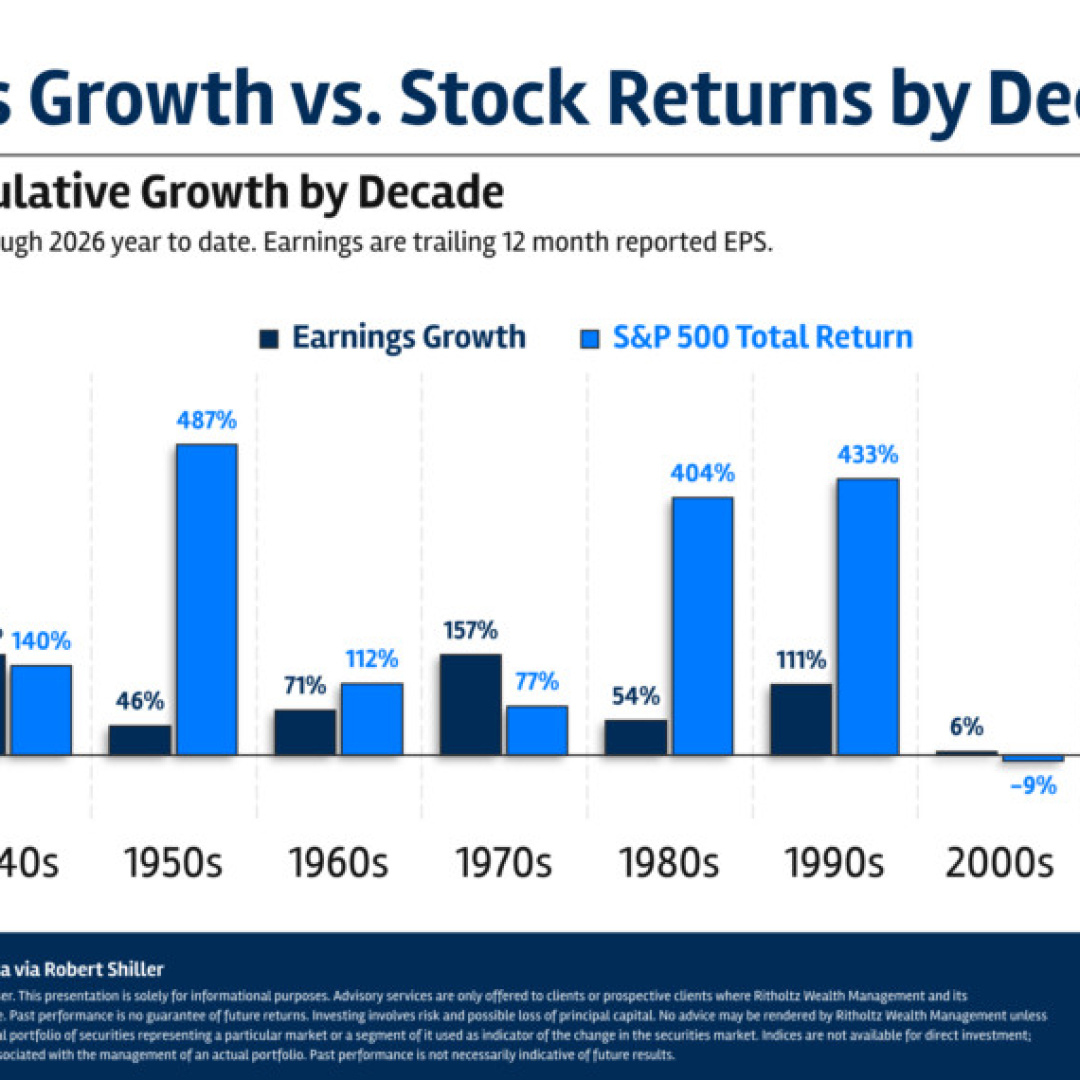
SK Hynix is currently trading at a forward price-to-earnings (P/E) ratio of 4 and a price/earnings to growth (PEG) ratio of 0.05, making it one of the most attractively priced stocks among the approximately 14 companies with a market capitalization of $1 trillion worldwide. Wall Street analysts forecast a remarkable 107% compounded annual growth in earnings per share (EPS) over the next five years, while the company recently reported a 76% operating margin in the last quarter.
In a strategic move, SK Hynix has announced a $28.6 billion share buyback and cancellation program, which effectively offsets its entire U.S. share issuance. This initiative alleviates concerns regarding potential dilution from the upcoming lockup expiration in October.
For Your Trading Desk
Sponsor Spike Success.
The trend of mega IPOs in 2026 has shown a predictable pattern, where companies initially experience a surge in demand, followed by a decline as market realities set in. SK Hynix's IPO on July 10, priced at $149 and opening at $170, followed this trajectory. After peaking at around $195 shortly after its debut, the stock fell below $125 as investors reconsidered the sustainability of the AI memory boom, a sector known for its cyclical nature.
Despite this volatility, SK Hynix's fundamentals remain strong. The company has seen a year-over-year revenue increase of approximately 41%, indicating robust performance that contrasts with the typical boom-bust cycle of memory chip stocks. Analysts from Bank of America suggest that while AI may not eliminate the cyclical nature of memory markets, it has extended the current upswing.
In May, SK Hynix crossed the $1 trillion market cap threshold on the Korean exchange, joining Samsung as the second Korean company to achieve this milestone. Currently, it is one of only a few stocks globally in this exclusive club, with its stock price at $162, making it cheaper than all but one other trillion-dollar stock.
The significant difference in valuation compared to peers like Micron Technology and Taiwan Semiconductor Manufacturing is noteworthy. With a forward P/E ratio under 4x, compared to Micron's 6.5x and TSM's 26x, SK Hynix's low PEG ratio suggests that the market has not yet fully recognized its earnings potential.
While factors such as a 'Korea discount' and limited access to U.S. markets contribute to this valuation gap, the company's strong operating margins indicate a potential mispricing that savvy investors might want to capitalize on. Wall Street's forecast of a 107% EPS growth rate over the next five years positions SK Hynix favorably among its trillion-dollar counterparts.
As the market prepares for the upcoming lockup expiration, the dynamics surrounding SK Hynix's share structure differ significantly from other recent IPOs. The U.S. listing consisted entirely of newly issued shares, with no insider selling involved, minimizing the risk of a significant sell-off.
In conclusion, while SK Hynix's stock has experienced the typical fluctuations associated with a mega IPO, its underlying fundamentals suggest a strong long-term investment opportunity for those willing to navigate the cyclical nature of the memory chip market.