Honeywell Gains $6.6B from Quantinuum Deconsolidation After IPO
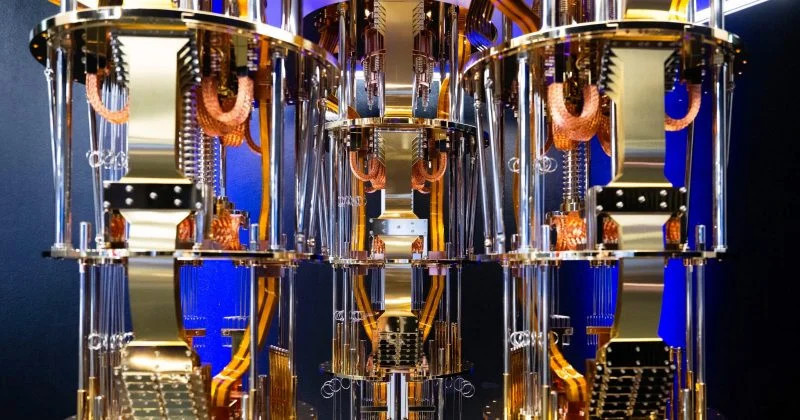
Honeywell has reported a remarkable $6.6 billion gain in its second-quarter earnings, primarily due to the deconsolidation of its quantum computing subsidiary, Quantinuum, which made its debut on Nasdaq on June 4 under the ticker QNT. This substantial gain is a one-time accounting event resulting from Honeywell relinquishing majority control of Quantinuum, which necessitated marking the remaining stake at fair value according to US GAAP rules. If the fair value exceeds the book value, a gain is recognized on paper.
This windfall boosted Honeywell's GAAP diluted earnings per share to $17.83 for the second quarter, although adjusted earnings per share saw a 4% decline year-over-year, landing at $4.52. The company’s consolidated sales reached $9.72 billion, reflecting a 4% increase compared to the previous year, with a segment margin of 23.1%.
For Your Trading Desk
Sponsor Spike Success.
Quantinuum's IPO was priced at $60 per share, opening at $68, marking a 13.3% increase on its first trading day and valuing the company at approximately $17.6 billion. Honeywell retains about 48.1% of the voting power in Quantinuum, having not sold its stake but rather reduced its ownership below the majority threshold, which alters the accounting treatment.
Quantinuum was established through the merger of Honeywell's quantum computing division and Cambridge Quantum. By taking Quantinuum public and decreasing its stake, Honeywell will no longer consolidate Quantinuum's operating losses into its income statement. This change is expected to provide a clearer view of Honeywell's core industrial business moving forward, allowing analysts to focus on its primary segments without the complexities introduced by a quantum computing startup.
The valuation of Quantinuum remains crucial for Honeywell, as its 48.1% stake means that fluctuations in QNT's share price will directly impact Honeywell's balance sheet. A rising share price enhances Honeywell's financial position, while a decline below the IPO price could necessitate a markdown of the minority stake, potentially affecting future earnings.